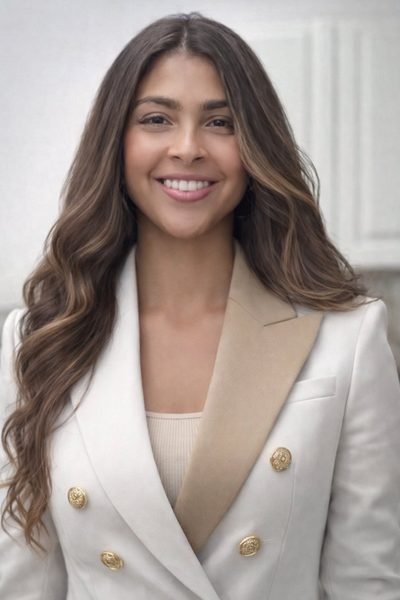
Karina A. Vasquez, Esq.
Georgetown Law · Admitted in Florida, North Carolina and D.C. Bilingual
You work with Karina directly. No associates, no paralegal hand-off.
The SBA is not a single loan. It is 7(a), 504, Express and the small working capital products, franchise and multi-unit lending, and rural lending under the USDA guaranty, and each program carries its own eligibility conditions, occupancy rules and closing file. A structure that is routine under one of them is ineligible under another, and that question gets decided by the documents long before a lender reads them.
The firm handles the legal side of SBA transactions from the letter of intent through the closing table. Business acquisitions, partner buyouts, owner-user real estate, expansion and working capital, franchise purchases, construction and refinance, drafted against the program the file is actually going into and closed alongside the lender's counsel.
A credit-approved SBA file rarely falls apart on the credit. It falls apart because a document signed months earlier cannot be made to comply with a rule nobody read it against.
The letter of intent is where the structure of the deal is actually decided. By the time a term sheet is issued, the purchase form, the seller note and the source of the equity injection have already been described to the lender and built into the credit memorandum. Changing any one of them afterward sends the file back through credit, and a file that goes back through credit in month four frequently does not come out in month five.
The documents that cause this are ordinary. A purchase agreement drafted as an asset sale when the reason to buy the company was its S election. A seller note signed at the letter of intent stage with a subordination clause instead of the SBA's standby language. An operating agreement that does not say who can sign for the buyer. None of these are difficult to get right at the start, and all of them are expensive to fix at the end.
This firm is engaged at the letter of intent rather than at closing. The purchase documents are drafted against the current SOP and against the lender's own closing requirements from the beginning, so the file that arrives at the closing table is the file the lender's counsel already expected to receive.
Ranges reflect common delays in SBA change-of-ownership closings generally. They describe the market and are not statements about any particular lender, transaction or outcome.
Each program carries its own eligibility conditions, and those conditions decide what the purchase documents have to say. The firm drafts to the program the deal is actually going into rather than to a general form.
Business acquisition, partner buyout, expansion, working capital, equipment and real estate purchase in a single facility. The most flexible of the SBA products and the one most acquisitions close under.
Owner-occupied commercial real estate and long-life equipment, structured as a conventional bank first mortgage behind a CDC second. Longer terms and a fixed rate on the debenture, with no cap on total project size.
Buying an operating company, buying out a partner, or acquiring a competitor. Goodwill is financeable, and real estate and working capital can be folded into the same facility rather than carried as a second loan.
Purchase, refinance or construction of the building the business occupies, at long amortization with no balloon. The operating company has to occupy 51 percent of an existing building or 60 percent of new construction.
Working capital, inventory, staffing and marketing on the Express track, with a mid-tier product that adds full 7(a) uses including debt refinance and a business purchase at Express speed.
Existing qualified debt refinanced under the 504 program to 90 percent of fair market value, with eligible business expenses included. The program cannot be used to put cash in an owner's pocket.
Acquisition, new build and territory expansion for franchise operators. The franchise agreement is read for the control provisions that create affiliation, because the lender now makes that determination itself.
Retirement funds used to capitalize a purchase without an early withdrawal penalty. The structure requires a C corporation and a qualified plan that buys its stock, and it has to be built correctly at formation.
The USDA guaranty for businesses outside urbanized areas, reaching sizes and terms the SBA programs do not. Eligibility turns on the property's location rather than on the industry.
Program parameters are set by the lender and by the current SBA Standard Operating Procedure, and they change. Financing placement is a separate business activity carried on through Forman Capital Partners, where Karina Vasquez is a partner and general counsel. The work described on this page is legal work performed by the law firm.
Karina Vasquez sits on both sides of the same transaction. She is a partner and general counsel at Forman Capital Partners, a nationwide commercial capital advisory firm, where she leads the SBA practice.
That role puts her in the file long before it reaches a closing table. She sets the direction on how an SBA transaction is structured and taken to market, works the deal through underwriting with the lender, and sees what credit committees actually condition, which lenders hold delegated authority and move quickly, which ones have quietly closed a vertical this quarter, and what a submission has to contain on the first pass rather than the fourth.
Most of that information is not published anywhere. It is held by the people who close with those lenders repeatedly, and it decides more about a timeline than any provision of the Standard Operating Procedure does.
The documents get drafted against both sets of requirements at once. The SOP decides what is eligible. The individual lender decides what actually gets approved. Having both in view when the purchase agreement is written is the reason a file comes back with two conditions attached to it instead of nine.
Direction on structure, lender selection and execution across the firm's SBA transactions nationwide, from acquisitions and partner buyouts to owner-user real estate and franchise programs.
Delegated authority, industry appetite, hold size and whether a lender closes in house are what decide a timeline. Those answers come from having closed with the lender before.
The purchase agreement, the standby note, the entity documents and the leases are drafted knowing exactly which desk is going to read them and what that desk will condition.
The same attorney who structures the deal negotiates the documents and sits at the closing. There is no hand-off to an associate at the point where the file gets difficult.
Forman Capital Partners is a separate business from the law firm and capital placement is not the practice of law. Financing is arranged there under its own agreement, and legal representation is engaged separately in writing with KVasquez Law. A client is free to use either one without the other.
A buyer came to the firm on the purchase of a Midwest transportation and warehousing company. The file as it stood was not close to financeable, and the buyer had been told it was ready to submit.
The earnings in the operating statements did not reconcile to the filed tax returns a lender would receive alongside them. The equity injection had no identified source. The acquisition was structured through a holding company, which would have terminated the target's S election at closing and taken part of the reason to buy the business with it. And the company was in transportation, a sector most SBA desks had quietly stopped taking after four years of freight recession.
Karina took the file apart and told the buyer exactly what it needed, item by item, rather than sending it out and waiting to be declined. The earnings were rebuilt on a documented add-back schedule so the trailing number could be defended line by line against the returns. Partners were brought into the acquisition so that the injection existed, was sourced and was traceable, with a portion of the seller's paper placed on full standby for the life of the loan. The purchase was restructured so the buyers acquire as individuals, which is what keeps the S election alive through the closing. Coverage was presented on trailing earnings, with the growth plan carried separately as upside the credit does not depend on.
Rebuilt that way, the file was placed with a lender whose book is concentrated in hospitality rather than transportation. A deal that had been written off on its industry got read on its own numbers, which is the entire objective of structuring a file before it goes out rather than after it comes back.
This matter is described generally and without identifying information. Every transaction is different, and prior results do not guarantee or predict a similar outcome in any other matter.
Every item below is drafted or reviewed by the firm. The lists are what an SBA closing file actually contains, which is usually more than a buyer is told at the letter of intent stage.
These are the provisions that most often change a deal after it is signed. Each of them is a drafting decision at the letter of intent and a renegotiation at the closing table.
A change of ownership requires an injection measured against total project cost rather than purchase price, so fees and financed working capital count. At least half has to be the buyer's own unborrowed money, which is why the source of funds trail matters as much as the amount.
A seller note counts toward the injection only on full standby for the life of the SBA loan, meaning no principal and no interest paid in the interim, documented on the SBA's own standby agreement and signed by the creditor. A note that says it is subordinate does not qualify.
Eligibility now turns on a citizenship test applied to every direct and indirect owner, and the standard was tightened in 2025 and again in 2026. A single owner who does not qualify makes the borrower ineligible, so this is confirmed before anything else is drafted.
Where the seller exits entirely, the exit has to be real. No shares, no officer or director seat, no employment, and no compensation dressed as something else. A transition role is possible as an independent consultant at a stated rate within the permitted period.
An independent business valuation is required above the SOP threshold and whenever buyer and seller are related. Where the valuation comes in below the agreed price, the gap is closed with equity, with fully standby paper, or with a price reduction, and not by adding seller financing.
Where the target is an S corporation, the buyer's structure decides whether the election survives the closing. An acquisition entity sitting above the target can terminate it, and the loan documents will not undo that. This is settled before the purchase agreement is drafted.
Owners at or above the threshold guarantee the loan without limit, a spouse may be asked to sign depending on ownership and on what secures the loan, and the lender takes a lien on substantially all business assets. Each of these has terms worth reading before signature.
A real estate loan requires the operating company to occupy 51 percent of an existing building or 60 percent of new construction, with a plan to occupy more over time. The lease between the holding entity and the operating company has to be written to those terms.
The SBA no longer maintains a franchise directory, so the lender determines eligibility from the franchise agreement itself. The provisions that matter are the ones giving the franchisor control over employment, suppliers and the sale of the unit.
The SBA Standard Operating Procedure is amended regularly and several of these requirements changed in 2025 and again in 2026. Every provision above is confirmed against the version in effect on the date your loan is numbered, which is the version that governs your file.
A fifteen-minute call at no charge, covering what is being bought, who is buying it, where the injection comes from and what the seller expects to keep. If the deal has an eligibility problem, it surfaces here rather than in month three.
The letter of intent is drafted or revised so that the purchase form, the seller note and the injection are already compliant when the lender reads them. The economics stay the client's decision.
Purchase agreement, entity documents, leases and the corporate record are drafted and the diligence responses are organized against the lender's checklist. Lien and title issues are cleared while credit is still working.
Closing is coordinated with the lender's counsel, the CDC on a 504 transaction, and the title or escrow agent. The client receives a closing binder and a corporate record that is complete, which is what the next lender or buyer will ask to see.
No, and this is the most common place a file arrives. A letter of intent is ordinarily non-binding as to the economics, which means the structure described in it can usually still be corrected. The sooner it is reviewed the smaller that correction is, because the terms have not yet been built into a credit memorandum.
The lender's counsel represents the lender. That attorney's job is to document the loan and confirm the SBA's conditions are satisfied, and it is not to negotiate your purchase agreement, your non-compete, your guaranty, or the lease between your entities. Those documents are yours and they outlast the loan.
It depends on what makes the business worth buying. Licenses, contracts, a favorable lease and a tax election usually argue for buying the entity. Unknown liabilities and a step up in the tax basis of the assets argue for buying the assets. The SBA adds its own constraint, because a partial change of ownership has to be a purchase of equity rather than of assets. This is decided before the purchase agreement is drafted and not after.
Those are two different questions. A seller may remain as an independent consultant for a limited period at a stated rate, which is how most transitions are handled. A seller keeping equity turns the deal into a partial change of ownership, which carries its own form and guaranty requirements and has to be structured that way from the beginning.
Partly. A seller note can satisfy a portion of the required injection, and only if it is placed on full standby for the life of the SBA loan on the agency's own form. The remainder has to be the buyer's own unborrowed funds, documented back to their source. A note drafted as ordinary subordinated seller financing will not be credited.
The gap is closed with additional equity, with paper placed on full standby, or by reducing the price. It is not closed by adding seller financing on ordinary terms, and a structure that attempts it will not survive the lender's review.
Yes. A seller carrying standby paper is lending a meaningful amount of the purchase price on terms that pay nothing for years, and the documents deserve the same attention from that side of the table.
Transaction work is quoted as a fixed fee once the structure and the document set are known, which is usually at the end of the first call. The quote is given in writing before the engagement begins, so that legal cost is a known number in your sources and uses rather than an estimate.
The call covers what is being bought, how the purchase is structured, where the equity injection is coming from, and what the seller expects after closing. Where there is an eligibility problem, the firm says so on the call rather than after an engagement letter is signed.
Bring the letter of intent if one exists, and the lender's term sheet or checklist if the file is already in process.
1200 Brickell Avenue, Suite 1950, Miami, Florida 33131
By appointment only legal@kvasquezlaw.com
Consultations are held by telephone, by video, or in person at the Brickell office by appointment. Bilingual in English and Spanish.
Scheduling a consultation does not create an attorney-client relationship. Please do not include confidential details in the booking notes.
The firm responds within one business day.
How the firm works alongside SBA lenders, and the structuring decisions on acquisitions and partner buyouts that decide whether a deal closes on schedule.
What a lender asks for before funding, and why the corporate record is usually the thing holding up the closing.
Why the minute book and the operating agreement get read closely by a lender, and what they are looking for in them.
By providing a telephone number to KVasquez Law, you consent to receive telephone calls and text messages at that number from the firm regarding your inquiry or matter, including messages delivered using automated technology. Consent to receive text messages is not a condition of retaining the firm or of any purchase.
Message frequency varies. Message and data rates may apply. Reply STOP to any message to opt out of text messages, or HELP for assistance. Opting out of text messages does not opt you out of telephone calls or email regarding your matter.
Text messages and email are not secure and are not confidential. Do not transmit sensitive, privileged or confidential information by text message. Communications with the firm do not create an attorney-client relationship, which is formed only upon a written engagement agreement signed by both the client and the firm.
Mobile information will not be shared with third parties or affiliates for marketing or promotional purposes. Text messaging originator opt-in data and consent are not shared with any third party. The Brickell office is by appointment only.
Karina A. Vasquez, Esq. is admitted to practice in Florida, North Carolina and the District of Columbia. Federal tax matters are handled nationwide before the Internal Revenue Service. Remote and virtual representation is available to clients across Florida, North Carolina and Washington, D.C.
The information on this website is provided for general informational purposes only and does not constitute legal advice. Viewing this website, submitting a form, or contacting KVasquez Law does not create an attorney-client relationship. An attorney-client relationship is formed only upon execution of a written engagement agreement. Do not send confidential information until such an agreement is in place. Prior results do not guarantee a similar outcome.